Is Now a Good Time to Buy Property in Brisbane? What We're Seeing on the Ground
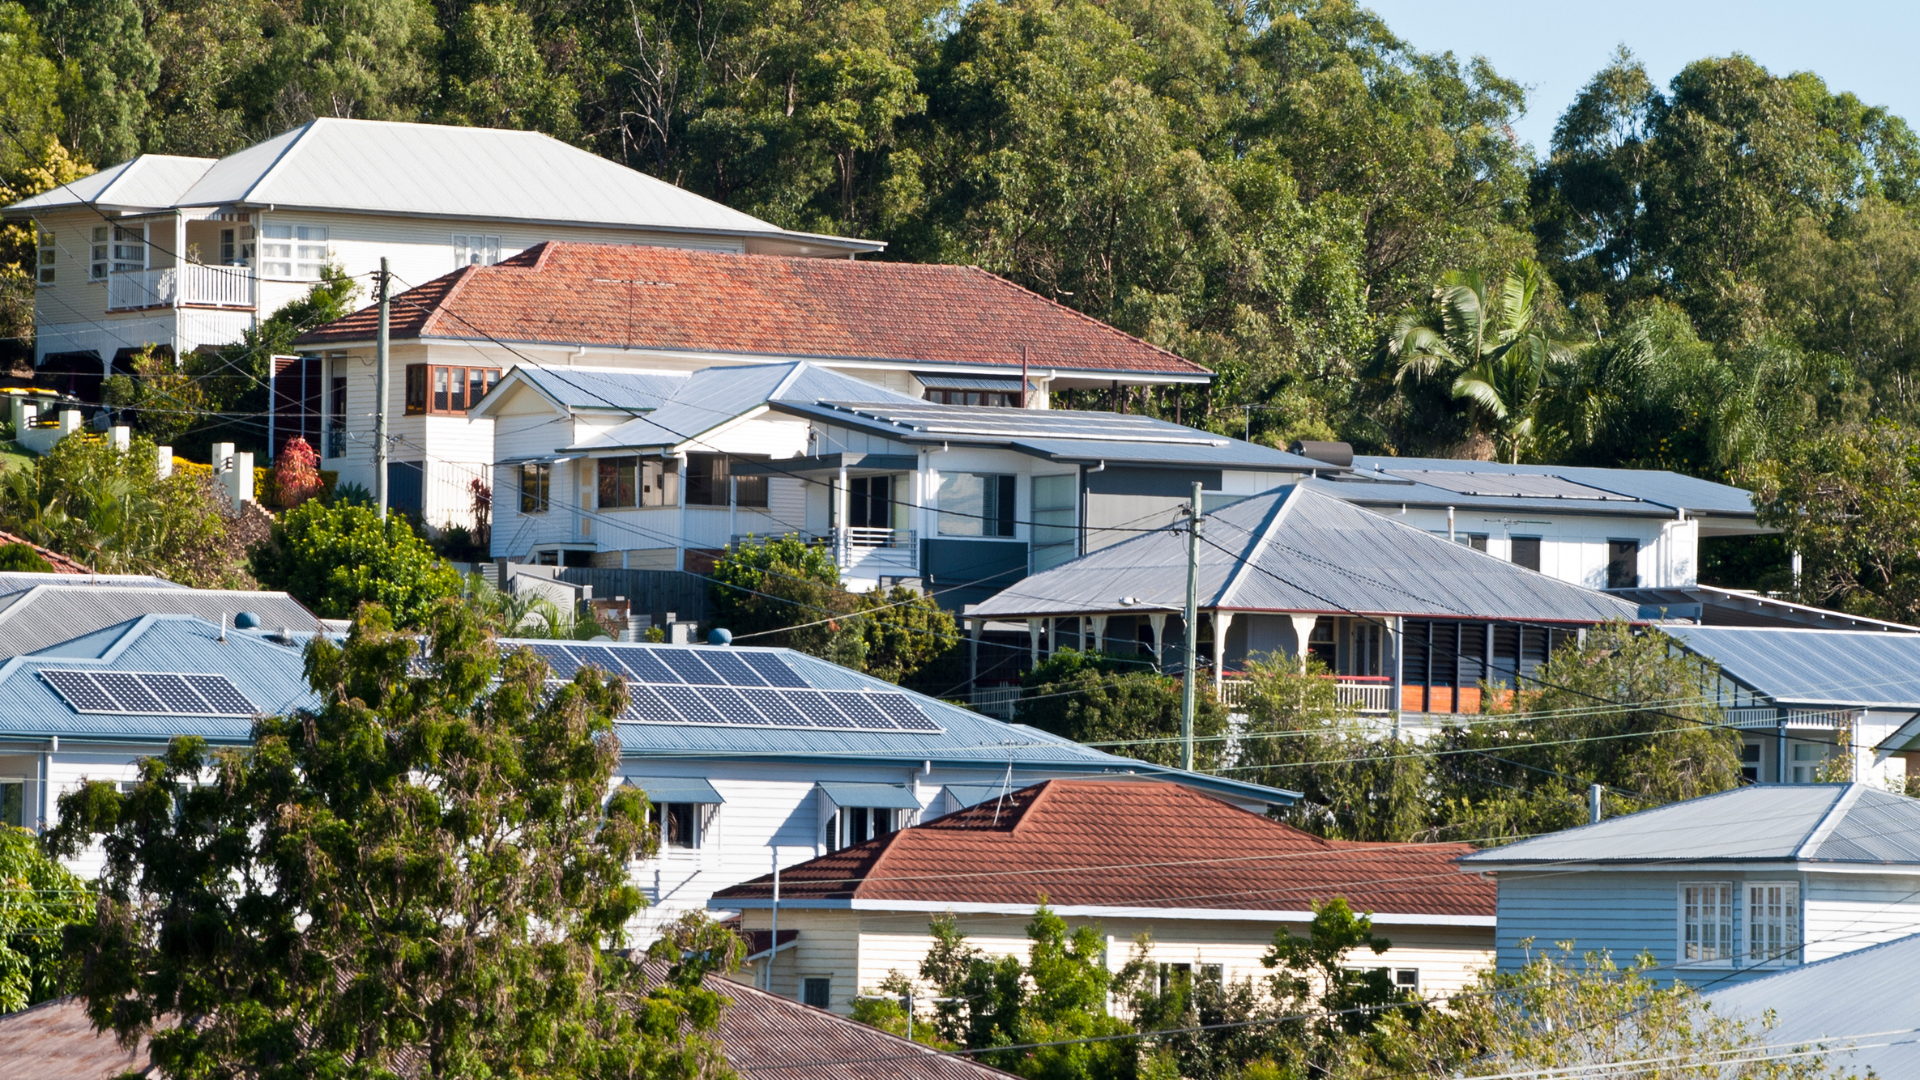 Brisbane's
property market has changed considerably in 2026. Interest rates are higher, borrowing capacity has tightened, auction clearance rates
have weakened and buyers are becoming more selective about both the properties they pursue and the prices they are prepared to pay.
For investors, this naturally raises the question of whether now is a good time to buy property in Brisbane.
There is no useful city-wide answer to that question. Current conditions may provide better buying opportunities in some parts of the market, but they have also increased the cost of holding property and placed greater pressure on household borrowing capacity. Whether an acquisition makes sense now depends on the individual property, the market in which it sits, the price being paid and the investor's capacity to comfortably hold it.
The Reserve Bank increased the cash rate to 4.60% in September 2026, adding further pressure to borrowing costs. Brisbane has not escaped the effects. Price momentum has softened and auction results suggest buyers have considerably more room than they did when competition was stronger.
We recently saw those conditions play out first-hand at a Brisbane auction, in circumstances that subsequently attracted coverage from The Courier-Mail, news.com.au and realestate.com.au.
The story was unusual enough to make the headlines. What happened around the auction, however, provides a useful snapshot of the market investors are navigating today.
What is happening in the Brisbane property market in 2026?
Higher interest rates are having a direct impact on the amount Australians can borrow and the cost of servicing existing debt. For property investors, this affects both sides of the transaction. Prospective buyers may have less borrowing capacity, while existing owners face higher repayments and greater holding costs.
The RBA increased the cash rate target by 25 basis points to 4.60% on 29 September 2026 following continued inflation pressure. For borrowers, another rate increase means finance needs to work harder before an investment property even enters the equation.
These conditions are now showing in property data. National home prices fell again in September, marking six consecutive months of declines according to realestate.com.au's Home Price Report. Brisbane, which had previously demonstrated greater resilience, has also experienced softer conditions.
Auction results provide another measure of buyer confidence. Brisbane's clearance rate has remained below 40% for an extended period, with recent results among the weakest of Australia's capital cities. A lower clearance rate doesn't mean there is no demand for Brisbane property, but it does suggest a larger proportion of transactions are failing to meet the expectations of either buyers or sellers.
For investors, this can provide more room to negotiate. It can also expose weaknesses that were easier to overlook in a rapidly rising market.
Is Brisbane currently a buyer's market?
There are certainly parts of Brisbane where buyers have more negotiating power than they did previously, although describing the entire city as a buyer's market is too broad to be particularly useful.
Brisbane contains hundreds of individual property markets. Conditions vary between suburbs, property types, price brackets and even streets. An established house on a well-positioned parcel of land in an area with limited future supply can behave very differently from an apartment in a location with a substantial development pipeline.
The condition of the property also influences the depth of the buyer pool. A house requiring significant work may struggle to attract buyers in a market where renovation costs and borrowing costs are both high, while a completed property nearby may continue to attract strong owner-occupier competition.
This is why city-wide median movements need to be treated as context rather than an investment strategy. The Brisbane median can tell us something about the direction of the broader market, but it cannot tell an investor whether a particular property represents good value.
That assessment needs to happen at the market, suburb, street and individual property level.
What a recent Wooloowin auction showed us about buyer confidence
We saw current buyer behaviour first-hand recently when Ramsey Property Wealth co-founders Ewan and Stefanie Ramsey came across a property auction while walking with their children in Wooloowin.
They hadn't gone out looking for another property. When they arrived, however, bidding had stalled and the property presented an opportunity worth assessing.
After reviewing what they could about the property, considering the work it required and establishing the maximum price at which the project made sense, they registered to bid. The four-bedroom property was ultimately purchased for $1.21 million.
The circumstances attracted media attention and the purchase was subsequently featured by The Courier-Mail, news.com.au and realestate.com.au, which reported that the purchase price was approximately $290,000 below the property's valuation.
While the price made a good headline, the behaviour of the other buyers at the auction was arguably more relevant to the current Brisbane market.
There were interested buyers present. One prospective buyer attended with a buyer's agent but ultimately didn't bid. Another reportedly wanted the property but couldn't proceed with an unconditional purchase while their existing home remained unsold.
As Stefanie told The Courier-Mail and realestate.com.au after the auction, "The buyers were there. The idea was there, but the confidence was low."
One auction can't be used to draw conclusions about the entire Brisbane property market, but the experience illustrates something that is also appearing in broader market data. Interest in property hasn't disappeared. The financial capacity and confidence required to turn that interest into a transaction have changed.
Are higher interest rates creating opportunities for property investors?
Higher interest rates can reduce competition for property because buyers generally have less borrowing capacity and higher repayment obligations. Existing investors carrying substantial debt may decide not to add another property, while owner-occupiers may reduce their budgets or delay buying altogether.
For an investor with strong borrowing capacity, adequate cash buffers and the ability to comfortably hold another property, a smaller buyer pool can create opportunities to negotiate on assets that may have attracted considerably more competition in a stronger market.
However, a lower purchase price needs to be considered alongside the cost of holding the property. An investor buying in a high-rate environment is subject to the same higher borrowing costs affecting everybody else.
A property purchased at an attractive price can still place significant pressure on a portfolio if the debt required to hold it is too expensive. Conversely, paying a competitive price for a high-quality asset may prove more valuable over the long term than buying a weaker property simply because it appears cheap.
For this reason, we don't view a falling market as a reason to buy in itself. The purchase price, quality of the asset, finance structure and cost of holding the property all need to work together.
Should property investors wait for interest rates to fall?
It is understandable that some investors would prefer to wait for lower interest rates before making another purchase. Lower rates would reduce borrowing costs and, in many cases, improve borrowing capacity.
The challenge is that lower rates don't occur in isolation. If borrowing capacity improves and confidence returns, more buyers may re-enter the property market. Increased competition can then place upward pressure on the prices of desirable assets.
Buying while rates remain elevated presents a different set of considerations. An investor needs to be confident that the property can be comfortably held at today's borrowing costs without relying on future rate cuts to make the numbers work.
At Ramsey, we prefer to assess an investment against the conditions that exist at the time of purchase. This includes stress-testing the lending position and understanding how the portfolio would perform if elevated borrowing costs persisted for longer than expected.
If an investment only becomes comfortable once rates fall, the assumptions behind the acquisition deserve closer examination.
Are Brisbane property prices falling in 2026?
Brisbane property prices have softened in 2026 following several years of much stronger performance. City-wide figures, however, conceal considerable variation between individual markets and assets.
Performance can differ according to suburb, dwelling type, land component, price bracket, local housing supply, rental demand, buyer demographics and the future development pipeline. Even within a single suburb, two properties can experience very different levels of demand depending on their location, condition, land and appeal to future buyers.
A declining Brisbane median therefore doesn't mean every property has fallen by the same amount. In the same way, a suburb with a strong historical growth rate isn't automatically a good place to invest today.
Our research team looks beyond the headline movement to understand the economic, demographic and housing conditions contributing to it. For investors, understanding why a market is moving can be far more useful than simply knowing whether the median price increased or decreased in the previous month.
What makes a Brisbane property a good investment in the current market?
In a softer market, asset selection becomes increasingly important. Investors can't assume that broad market growth will compensate for weaknesses in the property they purchase.
We begin with the underlying market. Population growth is useful, but it needs to be considered alongside employment, household incomes, infrastructure investment, housing supply, owner-occupier demand and the characteristics of the people likely to compete for that property in the future.
Supply also needs to be examined locally. Australia's broader housing shortage doesn't mean every suburb or dwelling type is undersupplied. Investors need to understand what is currently being built, what has already been approved and how easily additional housing can be supplied if demand increases.
The property itself then needs to withstand scrutiny. Land, layout, condition, street position, future buyer appeal and how the property compares with surrounding stock can all influence its long-term performance.
Price remains important. Even a high-quality property can become a poor investment if an investor significantly overpays. Comparable sales help establish an appropriate acquisition range, while a predetermined maximum price can prevent competitive negotiations or auctions from pushing the purchase beyond the point at which the investment case makes sense.
Cash flow and finance need to be assessed at the same time. Debt repayments, rental income, rates, insurance, management fees, maintenance and unexpected costs all contribute to the real holding position. Investors also need to consider what another acquisition does to their ability to borrow and make further portfolio decisions in the future.
Finally, the property needs to have a clear role within the portfolio. An investor seeking growth may require a very different asset from someone who needs stronger income or greater diversification. An investor already heavily exposed to one city or market may also need a different strategy from someone making their first acquisition.
There is no single property that is right for every investor. The asset needs to make sense within the investor's broader financial position and long-term strategy.
Why softer markets place more emphasis on preparation
Strongly rising property markets can be forgiving. When values are increasing rapidly across a large number of locations, investors can achieve capital growth even when the original acquisition was relatively ordinary.
Softer markets tend to expose the difference between assets more clearly. Property selection, purchase price, lending structure and holding capacity carry more weight when broad market growth can no longer be assumed.
Our recent Wooloowin purchase provided a very public example of this. We were able to assess the property quickly because we understood the local market, had experience assessing renovation and property risk, knew our financial position and established the maximum price we were prepared to pay before continuing to bid.
Being prepared to walk away was as important as being prepared to purchase. The objective wasn't to win an auction. It was to own the property only if the numbers remained within the range we had established.
For investors, preparation works in much the same way. Knowing borrowing capacity, portfolio cash flow, target markets and acquisition criteria before finding a property can make it easier to assess an opportunity when it appears.
So, is now a good time to buy property in Brisbane?
Current Brisbane conditions may provide good buying opportunities for some investors, particularly where softer competition creates room to negotiate on quality assets. For others, the appropriate decision may be to hold existing property, restructure debt, improve cash flow or wait until their financial position is stronger.
Higher borrowing costs, softer prices and weaker buyer confidence create both opportunities and risks. Investors therefore need to be selective about the properties they pursue and conservative about the assumptions used to justify a purchase.
Rather than deciding whether Brisbane as a whole is a market to buy or avoid, we believe investors should assess whether a particular property, at a particular price, improves their portfolio under today's conditions.
If the investment relies on rates falling quickly or property prices immediately recovering, the assumptions may need to be reconsidered. If the numbers work under conservative conditions, the asset suits the investor's strategy and the portfolio has sufficient capacity to hold it through different market conditions, then a softer market can be worth examining closely.
Our Wooloowin purchase wasn't made because Brisbane property prices had softened or because we were trying to call the bottom of the market. We bought because we understood the property, the price was within the range we had established and we were financially prepared to act when the opportunity appeared.
For investors considering their next purchase, that is a far more useful starting point than trying to predict the perfect month to buy.
Article Contributors
Written By:
Ewan Ramsey
Founder, Director and Investor
PhD research conducted by:
Dr Prabath Morawakage - PhD, CPA
PhD, Real Estate Finance and Economics at Ramsey
General information only. This material does not constitute personal financial, credit, tax or investment advice. Ramsey Property Wealth Pty Ltd | ACR 389087.
About Ramsey Property Wealth
Ramsey Property Wealth is an Australian property investment advisory firm helping investors build and manage property portfolios through portfolio strategy, finance advisory, PhD-led research and national buyer's advocacy.
Our process starts with the investor's existing position, objectives and portfolio before determining what, if anything, should be acquired next.
Considering your next property decision?
Before asking where to buy, understand what your portfolio needs next.
General information only. This article does not constitute personal financial, investment, legal or property advice. Individual
circumstances vary and appropriate professional advice should be obtained before making investment or property decisions. Australian Credit
Licence 389087.