RBA Raises Interest Rates to 4.85% on Melbourne Cup Day 2026: What Property Investors Need to Know
Did the RBA raise interest rates on Melbourne Cup Day 2026?
Yes. On 3 November 2026, the Reserve Bank of Australia increased the official cash rate by 0.25 percentage points, from 4.60% to 4.85%. The decision follows September annual inflation reaching 4.3%. For investors with multiple mortgages, the increase adds to borrowing costs and makes reviewing portfolio cash flow and lending arrangements increasingly important.
The increase comes after months of higher borrowing costs. Many established investors own four, five or six properties and have substantial equity, but the cost of holding those properties has increased. Some have seen rental income keep pace with expenses; others are contributing more personal income to their portfolios.
Why did the RBA raise interest rates again?
Inflation remains above the Reserve Bank’s 2–3% target range. The Australian Bureau of Statistics reported annual headline inflation of 4.3% in September 2026, up from 4.0% in August. Annual trimmed mean inflation reached 3.6%.
Higher interest rates are intended to moderate demand and help slow price increases, although monetary policy takes time to affect spending, business activity and inflation.
How much will the 0.25% interest rate increase cost property investors?
Consider an investor with $2.5 million in variable-rate investment loans. If lenders pass on the full 0.25 percentage point increase, the additional interest expense is approximately $6,250 a year, or $521 a month.
These calculations assume unchanged balances and represent interest costs, not an exact repayment quote. Actual repayment changes depend on loan structures, repayment types and lender decisions. The additional cost should be considered alongside rent, insurance, rates, maintenance and management expenses.
Will Australian interest rates rise further in 2026?
Further increases are possible, but future RBA decisions will depend on inflation, employment and broader economic conditions. Ramsey Property Wealth’s November research considers a cash-rate scenario of approximately 5.3–5.5%. This is for stress testing, not a prediction of the eventual peak.
For $2.5 million in variable-rate debt, a further 0.50 percentage point increase from 4.85% would add about $12,500 in annual interest if fully passed on. Investors should also consider rates remaining elevated for longer than expected.
Why can someone own five 5 investment properties but struggle to borrow again?
Property equity does not automatically establish borrowing capacity. Lenders assess income, existing liabilities, expenses, rental income and the ability to meet repayments under their lending criteria, including an interest-rate buffer.
An investor earning $350,000 annually and owning five properties may have considerable equity but still face serviceability limits.
Reviewing existing loans before pursuing another acquisition can clarify the options.
Should investors refinance after the November rate rise?
Refinancing may reduce borrowing costs or improve flexibility, but investors need to examine fees, loan features, repayment terms and the effect on future borrowing. For those holding several properties, a portfolio-wide review can be more useful than considering each loan separately.
Should I buy, hold or sell investment property now that rates are 4.85%?
The decision depends on the investor’s finances and existing assets. Manageable debt, sufficient reserves and strong rental income may support holding; significant annual cash contributions may warrant a review of expenses, lending or underperforming assets.
Any sale should also account for transaction costs, possible capital gains tax and local selling conditions.
What should property investors review following the RBA decision?
Review total rental income, interest expense, operating costs, current loan balances, upcoming refinancing dates and cash reserves. Model how the portfolio performs if rates rise another 0.25 or 0.50 percentage points or remain elevated.
For investors who have spent years accumulating property, it is also worth checking whether their existing portfolio still supports their
financial objectives.
The Ramsey perspective
The November increase undoubtedly adds costs to investor portfolios that may already be carrying substantial debt. So before deciding to sell, hold or purchase again, depending on your situation, investors should review the rental income, holding costs and contribution of each existing property.
Ramsey Property Wealth’s independent Portfolio Structure and Strategy Review supports estbalished investors during this time. The review, takes an independent approach helping investors assess what they already own and optimise their posotion, the review is standalone and not tied to buying another property, it examines the investors existing holdings, lending arrangements and longer-term objectives and our works through 3 pathways ultimatelyt support an investor on a let decision they need to make, do I buy, hold or sell in this market?
Start with the complimentary Property
Health Check
About the Contributors
Ewan Ramsey Founder and CEO, Ramsey Property Wealth
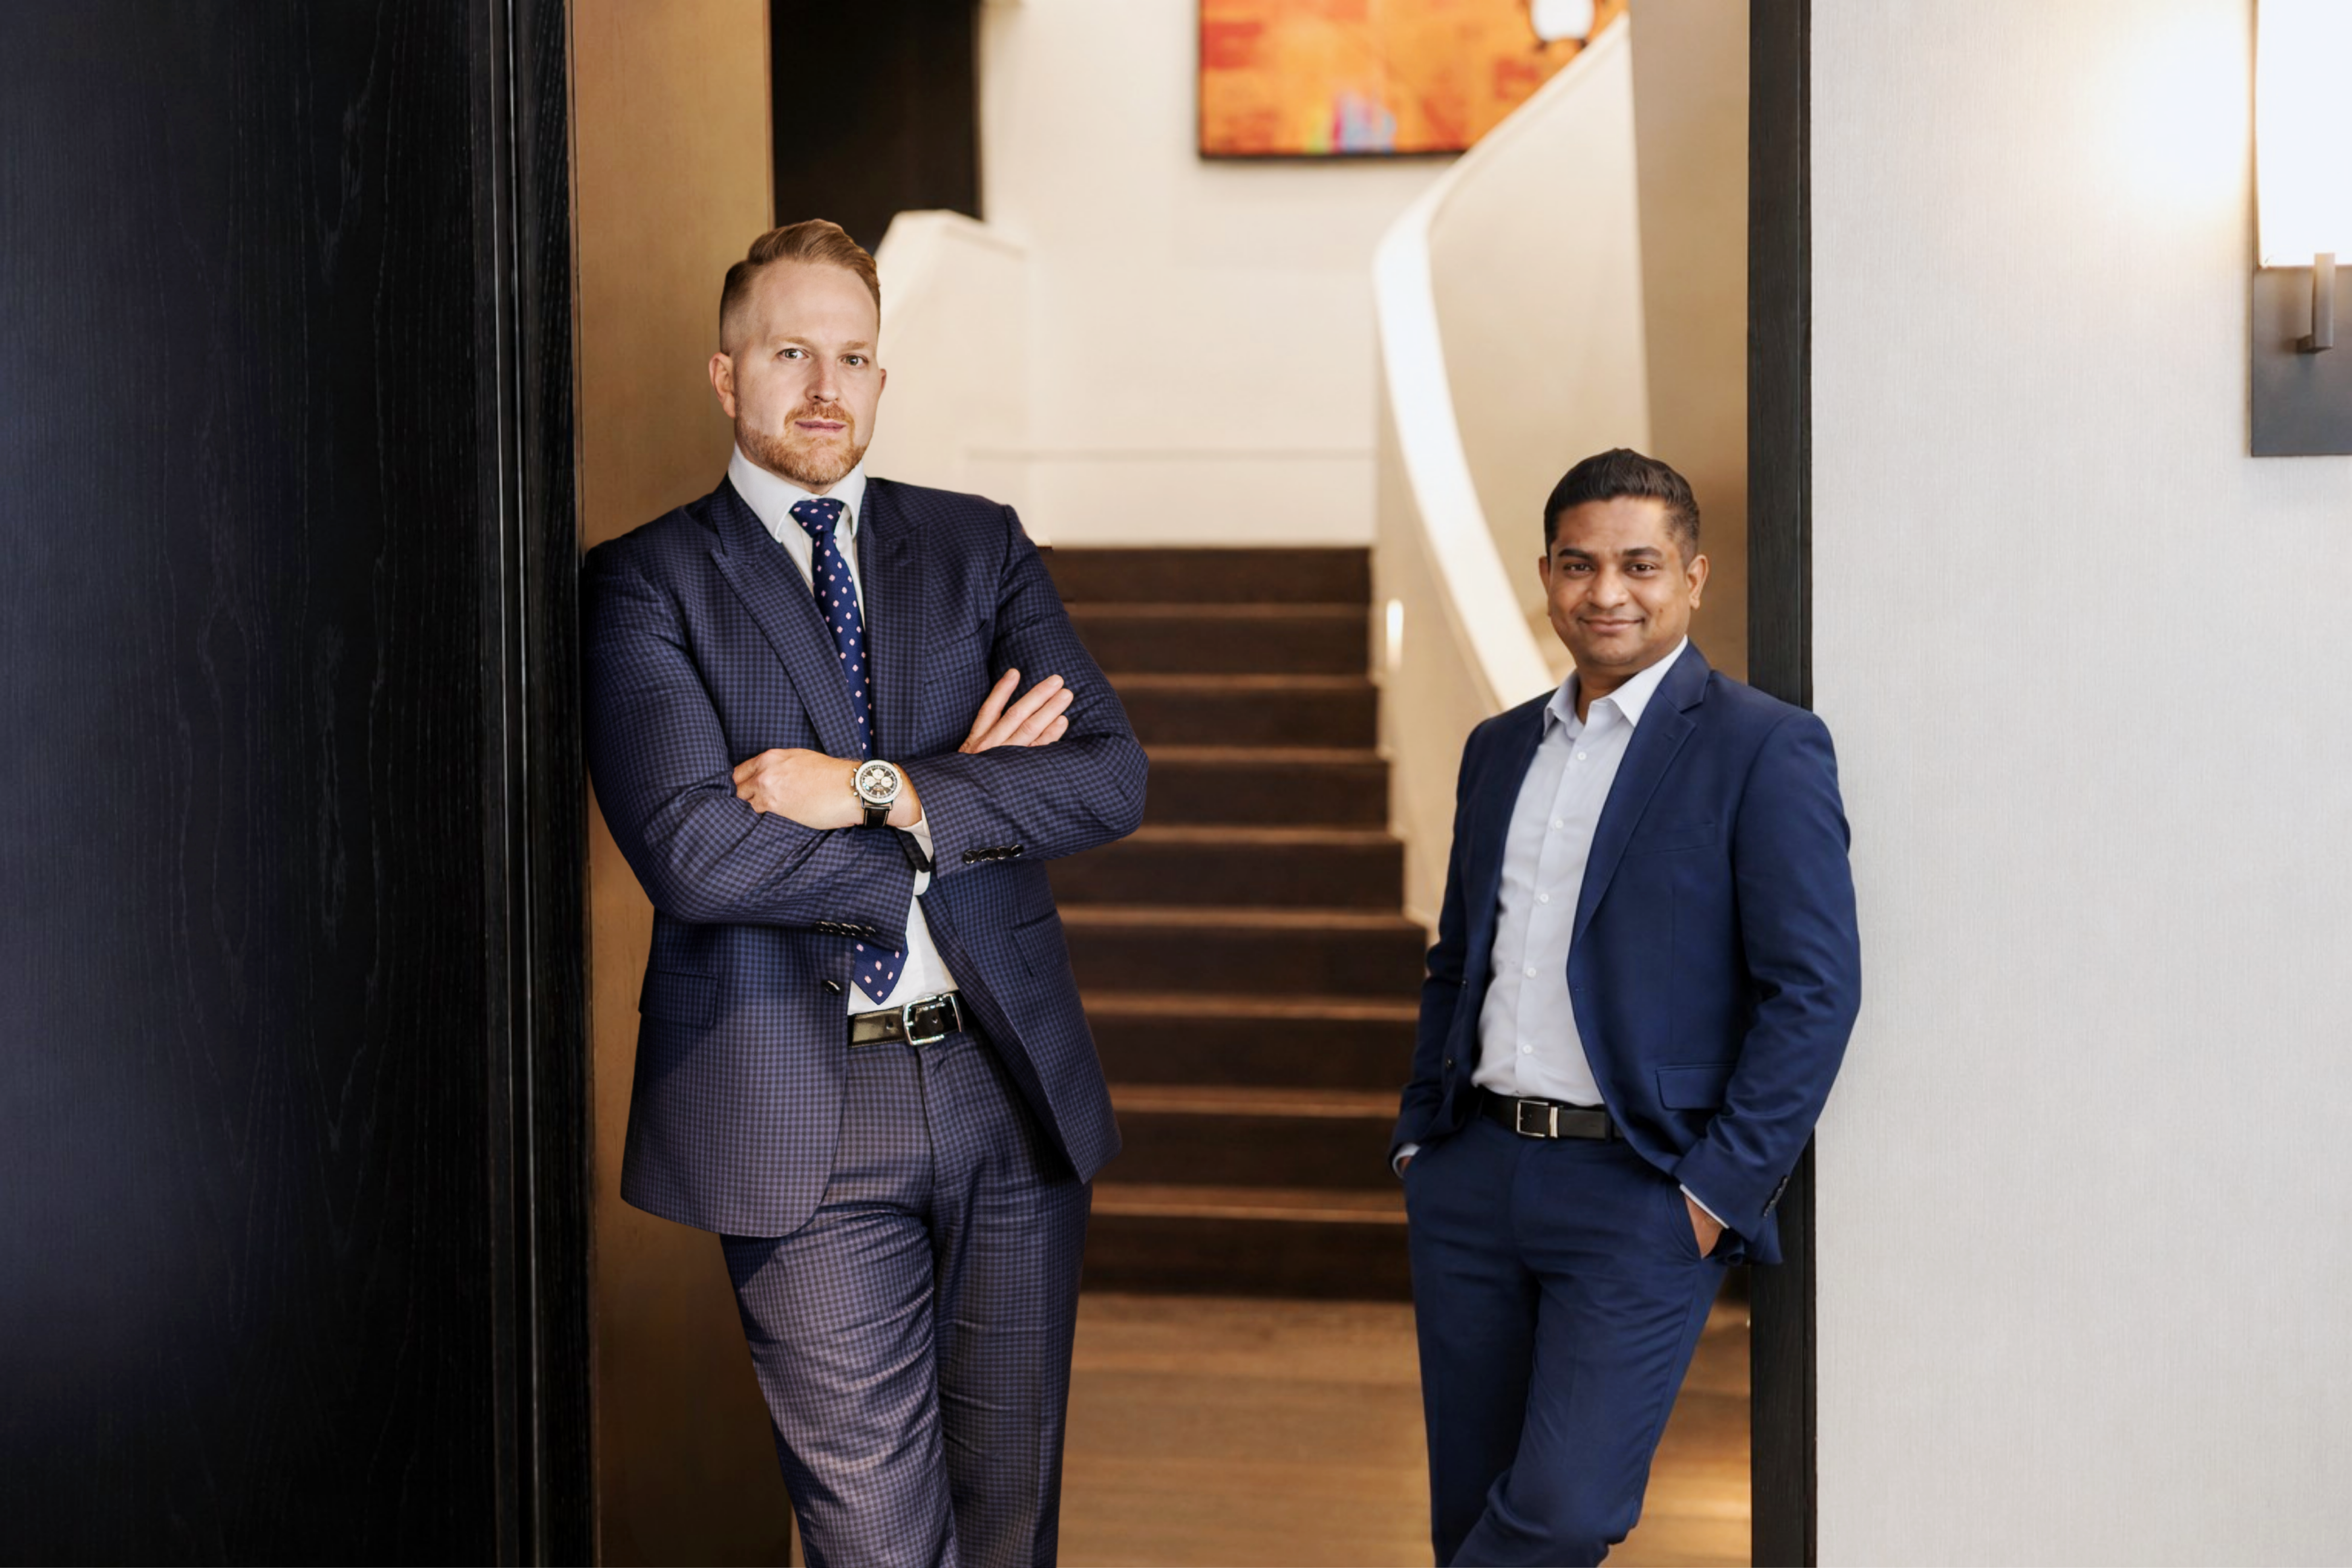 Ewan
founded Ramsey Property Wealth in 2018 to provide investors with independent, research-led property advice. He is the innovator and
orginator of our proprietary property portfolio modelling and works with established investors, professionals and business owners on build
and scale property portfolios via property portfolio planning, lending and acquisition strategy.
Dr Prabath Morawakage (PhD, CPA) Head of Research, Ramsey Property Wealth
Dr Prabath leads Ramsey Property Wealth's property research and economic analysis, examining Australian housing markets, inflation, housing
supply, rental demand and investment performance. Each and every Ramsey cleint has access to PhD grade property and finance research,
applied to their portfolios.
About Ramsey Property Wealth
Founded in Brisbane in 2018, Ramsey Property Wealth provides integrated portfolio planning, lending advice, acquisition and ongoing
portfolio optimisation.
Ramsey Property Wealth is Australia's only indpepedent, professional property wealth planning advisory firm.
Research Sources
Sources: Reserve Bank of Australia, Monetary Policy Decision, 3 November 2026; Australian Bureau of Statistics, Consumer Price Index, September 2026, released 28 October 2026.
General information only. This article does not consider your personal circumstances or objectives. Seek appropriate professional advice
before making investment or lending decisions. Australian Credit Licence 389087.