When does a property portfolio actually start paying you?
Author: Ewan Ramsey
Date: 19 November 2026
 A property portfolio starts paying you when the income it produces covers what it costs to hold it - when rent, after all costs and
tax, exceeds the loan and running expenses.
Reaching that point is a decision driven by 4 levers (rent position, loan structure, holding mix, and sequence), these are
manufactured from a professional, purposeful plan.
So
you've bought investment properties prior and you've carried them ubsude your portfolio for years. The fair question, and one that's
easy to avoid, is when is your portfolio going to start to paying you instead of the other way around.
The short answer: it pays you when the income it produces covers the cost of holding it, and getting there is something you decide and
engineer, not something you wait for.
That 's increasingly becoming more and more important this month than usual, because political and financial forces, and the market
has made is a little harder to bluff your way through.
Is the market making this harder right now?
Yes, and in a specific way. This is now the deepest housing downturn on the modern record, and it has changed character. It is no longer a
discussion about interest rates but turning into a credit story. Investor loan commitments collapsed 32.9% over the September
quarter, from $52.6 billion to $35.3 billion, and new home lending fell a record 15% (ABS
Lending Indicators,
per RPW's reading of the September release). Credit is the shock absorber an economy normally leans on when prices fall.
Right now it's the thing contracting the fastest in Australia, and so financial conditions are tightening on their own, whether or not
the Reserve Bank is finished their work.
Even a December pause on interest rates wouldn't loosen Australia's market conditions, because the tightening has moved past the
people and into the lending channel.
So when does a portfolio actually start paying you?
It starts paying you when the gap between what the properties earn and what they cost to hold closes and then turns positive. For most investors that gap is still open: investor variable rates now sit above 6%, and we stress-test every plan against an all-in floor near 8% (News-Cycle Scan, Nov 2026). If your rents have not kept pace with that, your salary is quietly subsidising the portfolio. You own the asset, but it does not yet pay you.
What moves an investment property portfolio from salary-supported to self-supporting?
A property portfolio doesn't necessarily become self-supporting simply because an investor has held it for a long time. The transition depends on how rental income, borrowing costs, property selection and financial decisions interact across the portfolio.
The Four Levers of Property Portfolio Cash Flow
1. Rental Income and Property Performance
Rental income needs to be assessed against the actual cost of holding each property. Vacancy periods, maintenance, insurance, management fees and changes in local rental conditions can materially affect the net income generated. A property with strong capital growth may still require ongoing contributions from the investor's salary.
2. Loan Structure and Borrowing Costs
Interest rates, loan terms, repayment structures and the allocation of debt across a portfolio directly influence cash flow. Reviewing lending arrangements can identify opportunities to reduce unnecessary financing costs, improve flexibility and strengthen the portfolio's financial resilience.
3. Portfolio Composition and Holding Decisions
Not every property contributes equally to a portfolio's long-term objectives. Some assets may provide strong growth potential but limited
income, while others may generate more consistent cash flow. Reviewing the contribution of each property helps investors determine what to
retain, improve, restructure or potentially sell.
4. Timing and Sequence of Financial Decisions
The order in which an investor makes decisions can be as important as the decisions themselves. Selling an asset, reducing debt, refinancing
or acquiring another property can produce materially different outcomes depending on when each action occurs. Modelling alternative
scenarios helps investors understand the potential effect on future cash flow and net property wealth.
Does the current market change the answer?
It sharpens it. With borrowing capacity and the number of competing buyers falling now, the marginal buyer who clears an auction is the
investor, and the investor is leaving fastest. Clearance rates have sat below 60% for more than six months (AFR
Property,
week of 9 Nov 2026).
A minority of buyers are starting to read the fall as an opportunity, but in a credit crunch it is the security of your finance, not
your conviction, that decides whether a move is an opportunity or a trap.
The same discipline that tells you when your portfolio will start paying you also tells you whether you have the capacity to act while
others can't.
Our view
The income transition is a decision. Those investors who research their position and shorten the decision making and measure the
gap on every property, fix the asset or structure holding the total back first, and act in sequence rather than all at once.
If you want to modelled your own situation, our in-house Economist Dr Prabath Morawakage has designed a complimentary Property
Health Check
tool exactly for investors like you. Enabling you to runs your particular property through the 3 hold, sell or restructure
scenarios above.
It only requires a few numbers you'd have with you, it's at no cost and no obligation.
Otherwise, for personalised, professional advice. Please click below to book a Discovery Call with our Advisors.
About the Contributors
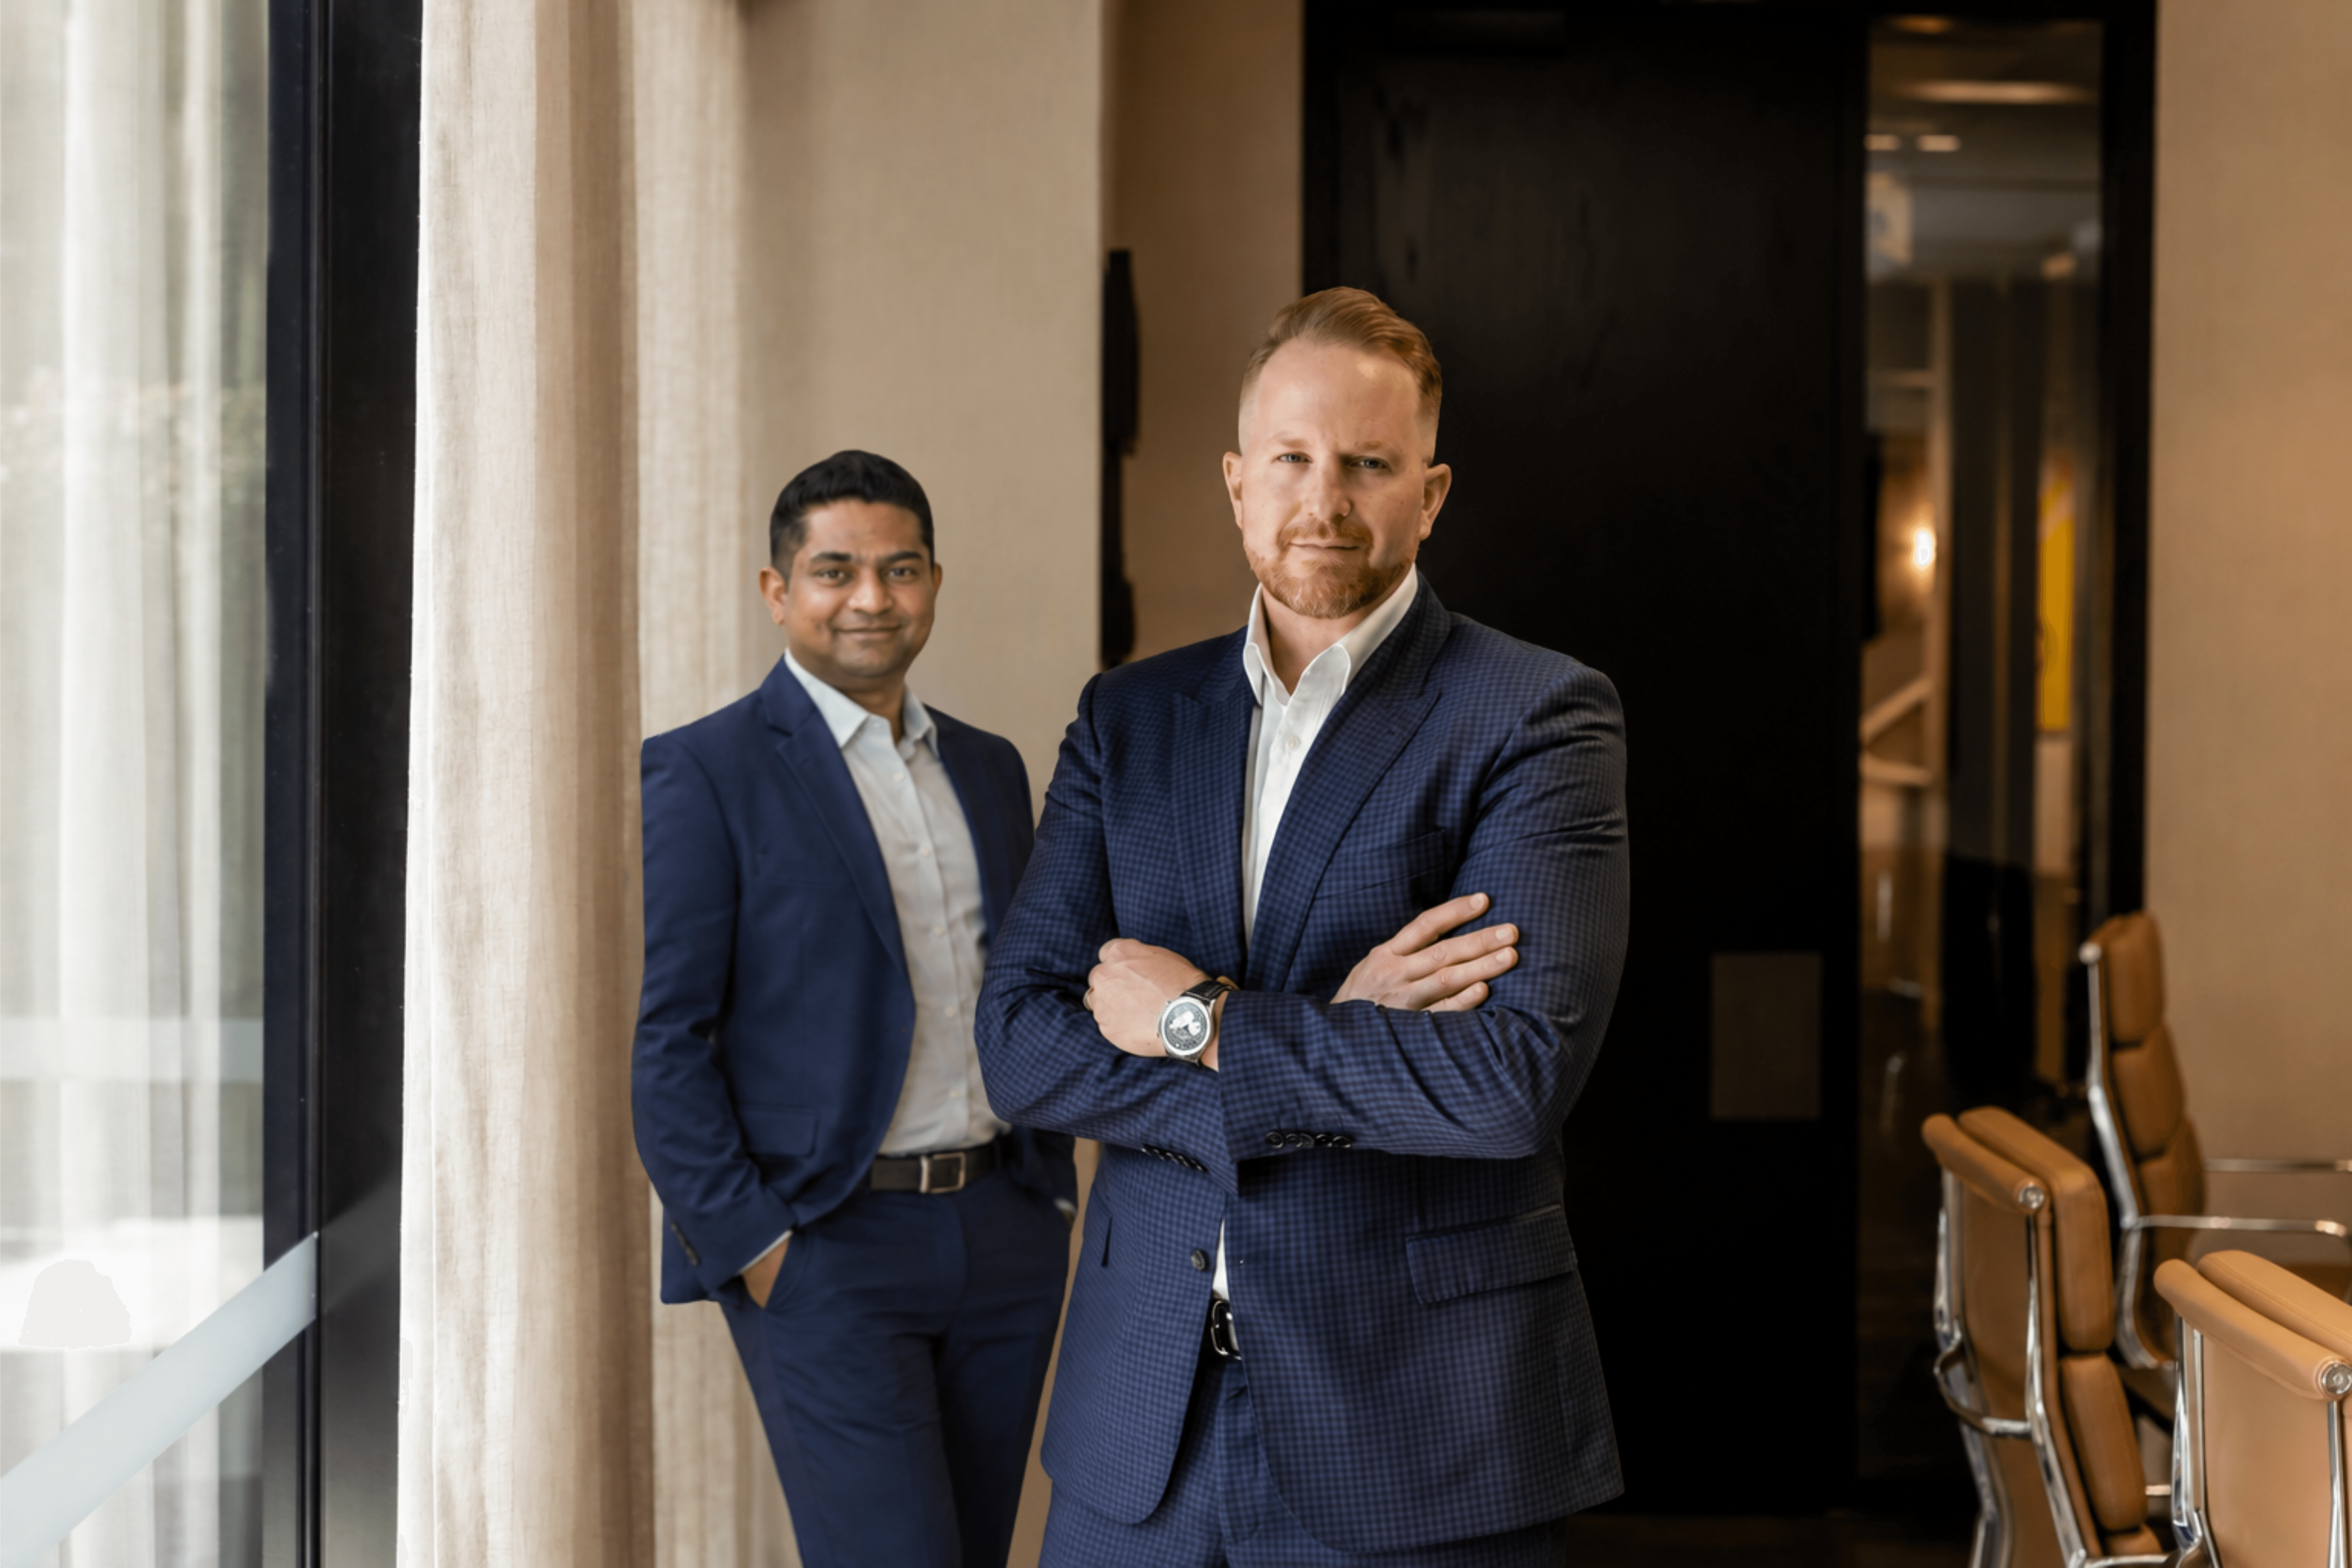 Ewan Ramsey Founder and CEO, Ramsey Property Wealth
Ewan Ramsey is the Founder and CEO of Ramsey Property Wealth, an
independent property wealth advisory firm established in Brisbane in 2018.
He works with established investors, high-income professionals and business owners to develop long-term property portfolio strategies,
with a focus on property performance, finance and acquisition decisions.
Ewan's contribution to this article considers how changing market conditions affect investors who already own multiple properties and are
assessing whether to buy, hold, sell or restructure.
Dr Prabath Morawakage (PhD, CPA) Head of Research, Ramsey Property Wealth
Dr
Prabath Morawakage
leads the firm's property research and economic analysis.His research examines economic conditions, Australian housing markets, property
supply, rental demand and the factors influencing investment performance.
Dr Morawakage's contribution to this article focuses on interpreting the latest market data and understanding the different conditions
affecting Australian property markets.
About Ramsey Property Wealth
Ramsey Property Wealth is an independent Australian property wealth advisory firm established in 2018.
The business provides astute investors and time-poor high income professionals with integrated property portfolio planning, property
finance advice, PhD economic and housing research-led acquisition and ongoing portfolio optimisation for established investors,
professionals and business owners.
Our work combines economic research with individual portfolio analysis to support informed property investment decisions.
Compliance: general information only, past performance is not a reliable indicator of future performance. Ramsey Property Wealth Pty Ltd, ACL 389087.