Why Can't I Borrow More Money Despite Having a High Income and Property Equity?
High income and substantial property equity don't automatically guarantee additional borrowing capacity. Australian lenders assess your ability to repay debt based on existing loans, income, expenses, rental income and lending policies.
This explains why an investor who owns millions of dollars in property may still struggle to secure financing for another investment.
Why Does Borrowing Become Harder as Your Portfolio Grows?
As property investors acquire more assets, their total mortgage commitments often increase.
Even when property values appreciate, existing repayments continue to affect borrowing capacity.
An investor may have a strong salary and substantial equity, but the lender still needs to determine whether they can afford another loan.
Property equity measures ownership value. Borrowing capacity measures the ability to service debt.
Understanding this distinction is essential for established investors.
What Do Australian Banks Consider When Assessing Borrowing Capacity?
Lenders generally examine:
- Employment or business income
- Existing mortgages and other debts
- Household and living expenses
- Rental income and associated costs
- Loan assessment rates and serviceability buffers
- Credit history and lender-specific policies
Different lenders may assess the same borrower differently, but substantial equity alone is not enough to establish eligibility.
Why High-Income Professionals Face Borrowing Challenges
Doctors, dentists, executives and business owners may have significant earning capacity but also carry complex financial commitments.
These can include multiple investment loans, business liabilities, personal expenses or variable income.
As their portfolios grow, borrowing capacity can become increasingly constrained.
This is why portfolio and finance planning become more important as investors accumulate assets.
Investor Scenario: A Medical Professional With Three Properties
Consider a medical professional earning $300,000 annually who owns three investment properties.
The properties have increased in value, creating substantial equity.
However, the investor also has multiple mortgages and significant financial commitments.
When applying for another investment loan, the lender determines that the additional repayments would exceed its serviceability limits.
Rather than immediately searching for another property, the investor may benefit from reviewing existing finance arrangements, cash flow and debt exposure.
What Should You Do When Borrowing Capacity Becomes Limited?
A structured review can help identify areas worth examining.
These may include existing loan structures, repayment commitments, property expenses and financial reserves.
The goal isn't necessarily to increase borrowing immediately.
It is to understand what is limiting financial flexibility and whether any appropriate changes are available.
Watch The Ramsey Report: Why Can't High-Income Investors Borrow More?
You could own millions of dollars in property and still struggle to secure another investment loan.
In the latest episode of The Ramsey Report, Ewan Ramsey and Dr Prabath examine why high-income professionals, including doctors, dentists, executives and business owners, can experience borrowing limitations despite substantial property equity.
They explain the difference between property wealth and debt serviceability, and why understanding your existing finance structure is essential before pursuing another acquisition.
Watch the full episode to discover why growing property wealth doesn't always mean greater borrowing capacity.
YouTube Button: https://youtu.be/vUNjKTWfzLg
Related Reading: What Should Investors Do When Rates Rise?
Borrowing capacity can become increasingly restrictive as investors accumulate more properties and financial commitments.
For further insight, read Interest Rates Have Risen to 4.60%. What Should Property Investors Do Now? This recent Ramsey article examines how interest rates can affect borrowing capacity, cash flow and investment decisions.
Article Contributors
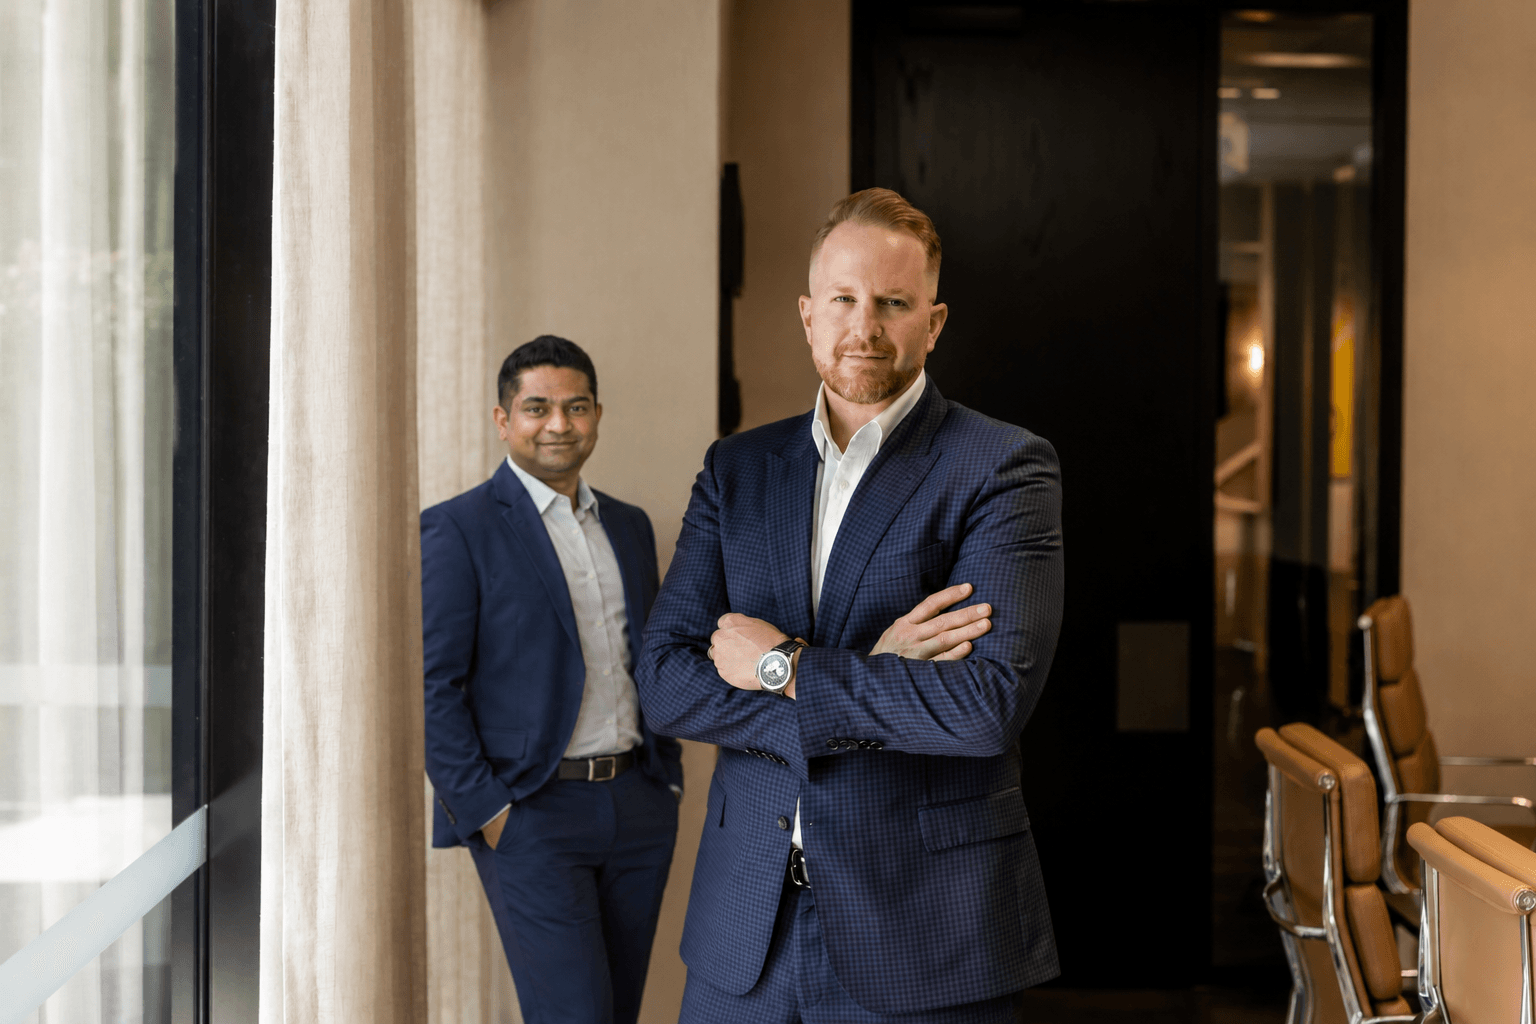
Written by: Ewan Ramsey
Founder and CEO, Ramsey Property Wealth
Research by: Dr Prabath Morawakage, PhD, CPA
Head of Property Economics and Intelligence, Ramsey
Property Wealth
Is Your Borrowing Capacity Holding Back Your Next Investment?
Review your existing finance arrangements and explore how your current borrowing position may affect future investment decisions.